
ByteTree Chief Investment Officer: Rising interest rates cannot shake the appeal of gold
Charlie Morris, chief investment officer at ByteTree, said that ignoring interest rate hikes and soaring bond yields, gold prices have become more closely tied to the global money supply.
Kitco News Finance Editor Ernest Hoffman writes about ByteTree Chief Investment Officer Charlie Morris' latest Atlas Pulse Gold Report.
Charlie Morris, chief investment officer at ByteTree, said that ignoring interest rate hikes and soaring bond yields, gold prices have become more closely tied to the global money supply.
Gold likes low interest rates, high inflation, a booming money supply and strong global demand, but it appears willing to shrug off rising interest rates, Mr. Morris said in his latest Atlas Pulse gold report. "Interest rates are soaring and gold prices don't care," he wrote. "Gold is sending a message."
Mr. Morris said he believed gold was undervalued given the money supply. "At the moment, the chart suggests gold is undervalued by about 5 per cent relative to the global money supply. That's a different way of thinking."
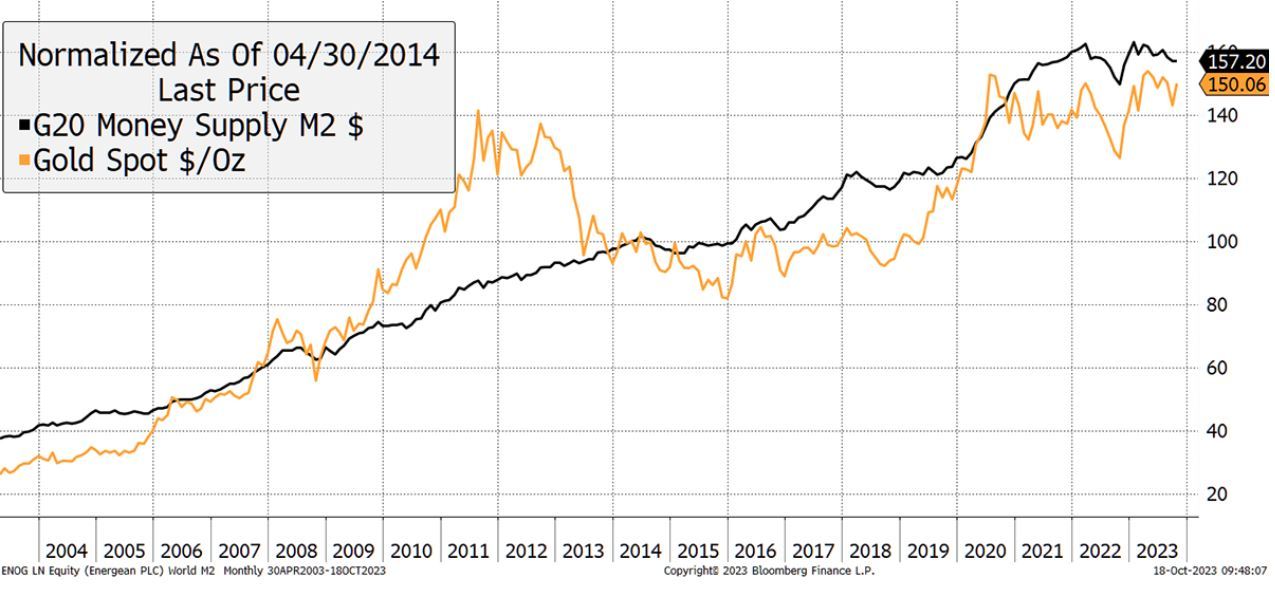
The point about the global money supply, he said, is that gold is a global asset, so it can tell people things that U.S. data can't tell you. "Traditionally, we use U.S. data for a lot of things, mainly because the U.S. is the largest economy, but more importantly, it has the best data available," he said. "It's not as appropriate as Global M2, but at least it has history."
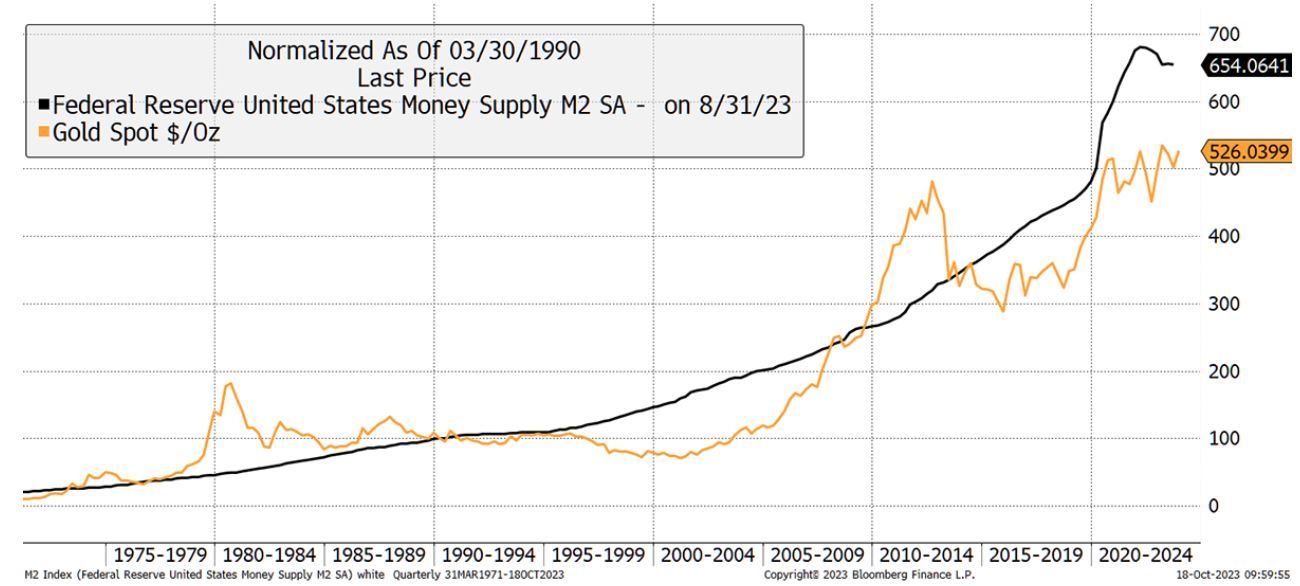
Gold prices have matched US M2 very well over the past 50 years, but "in 1960 the US was 40 per cent of global GDP; today it is 26 per cent," says Mr. Morris. "Leaving out 74 per cent of the data for financial analysis no longer qualifies."
But Morris pointed out that based on U.S. M2, gold still shows a 20% upside.
Morris also looked at potential reasons why gold is ignoring rising interest rates. "I've been concerned about the spike in interest rates and bond yields," he wrote. "These measures have eased inflation (or have they?) and caused real interest rates to fall (interest rates minus inflation). This is usually bad for gold, but this time it seems to be different."
To try to explain the discrepancy, Mr. Morris looked at politics, central bank demand, the mispricing of TIPS and potential bubbles. "My model for 20-year TIPS shows a huge difference, meaning gold is 58 per cent overvalued," he says.
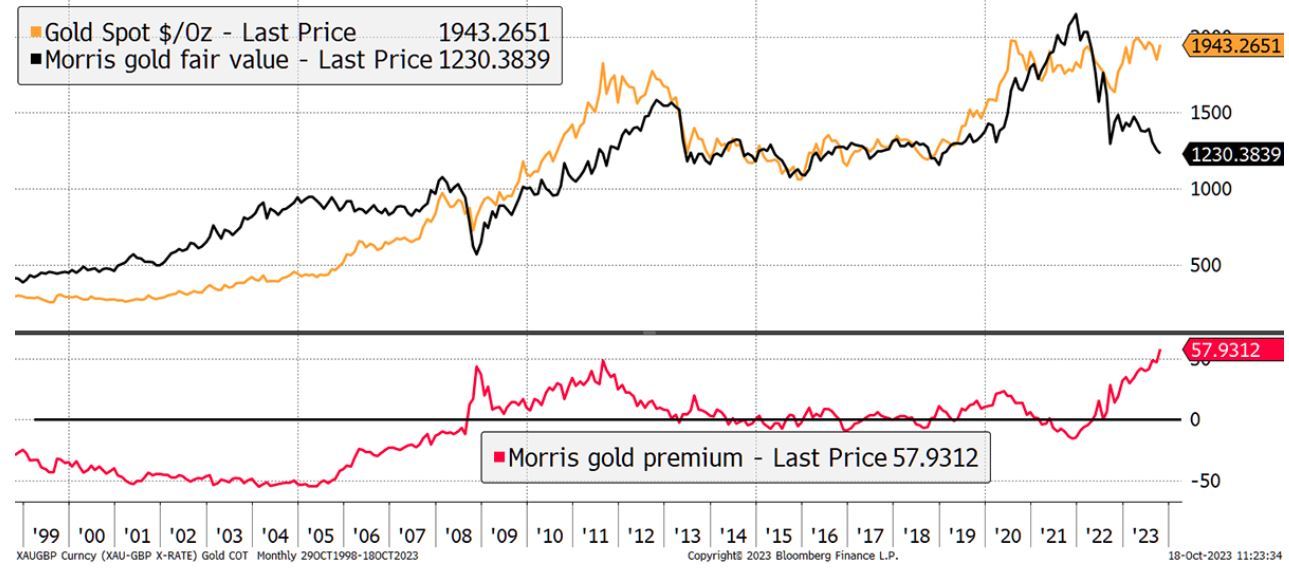
Morris concludes that this is a period of transition for gold. "This is not a bubble, but inflation-protected bonds are mispriced [too cheap] and understate inflation," he says. "Politically unstable, central banks are right to put gold over Treasuries. At least the supply is limited."
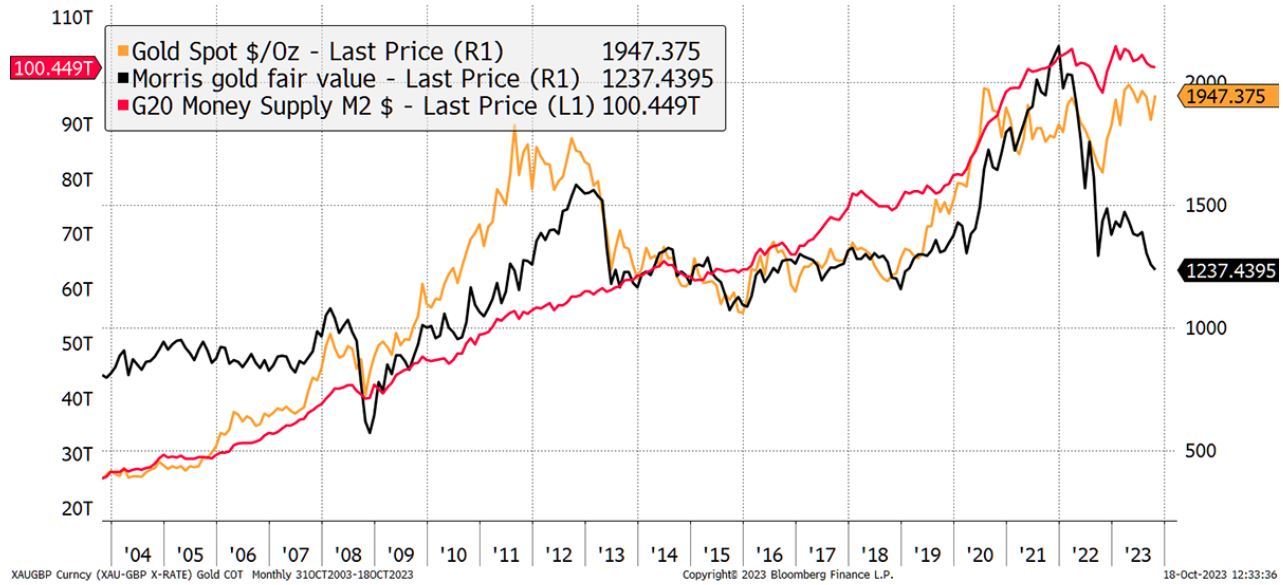
"As a long-term price determinant, therefore, gold is more closely tied to the global money supply than to inflation," he said. "In the medium term, real interest rates will remain the most important factor, but we are living in transition times."
Mr. Morris said long-term factors were more important than short-term factors at the moment. "I think the long-term driver for gold should be the money supply outstripping inflation because M2 expands as the economy grows and inflation will only rise as a result of economic mismanagement, which is theoretically optional," he said. "Gold is not just a hedge against inflation; it is an important asset whose value has to keep pace with wealth creation, even if it is counter-cyclical. But over the medium term, real interest rates have been a compelling driver of gold prices, and if ignored for a while, real interest rates will make a comeback."
Finally, "gold tells us that things are extraordinary," Morris added.
Please indicate the source: https://www.daoctech.com/fxnews/929.html
Disclaimer: The content of this article does not represent the views of the Institute of Foreign Exchange. The content is for reference only and does not constitute investment advice. Investors operate accordingly at their own risk.