
FX: The impact of Zhongrong Trust's thunderstorm on the market
1
Recently, there has been a steady stream of news about trust products.Since August, three listed companies have disclosed the risk warnings of overdue redemption of trust products, among which the trustees of the products are all involved in Zhongrong International Trust Co., Ltd.
Among them, there are 3 trust products overdue by Xianheng International, involving an amount of 63 million yuan, 2 trust products overdue by Jinbo shares, involving an amount of 60 million yuan, and 1 trust product overdue by Nandu property, involving an amount of 30 million yuan. Zhongrong Trust's products have a redemption crisis, and some investors are worried about other trusts or similar crises. Minmetals Trust and Everbright Trust issued an announcement to urgently refute rumors.
Zhongrong Trust, formerly known as Harbin International Trust and Investment Company, was changed to Zhongrong Trust in 2007. In 2010, Jingwei Textile Machinery transferred the share capital of Zhongrong Trust 117 million held by Zhongzhi Enterprise Group and became the largest shareholder. As of the end of last year, Jingwei Textile Machinery held 37.470% of Zhongrong Trust and was the controlling shareholder. Zhongzhi Enterprise Group held 32.986% and was the second largest shareholder. The actual controller of Zhongrong Trust is SinoMach.
Xie Zhikun's nephew Liu Yang served as the chairperson of Zhongrong Trust. The Zhonghua Group (suspension of payment) involves 150,000 high net worth investors, and the creditor's rights and interests 230 billion. The maximum amount of a single customer is more than 5 billion yuan, and the chairperson of Hengtian Wealth also holds 7 million such group creditor's rights products.
In the past three years, Zhongzhi Enterprise Group has taken the initiative to reduce the scale of its fundraising and reduce its debt ratio and costs.
In June 2023, due to the failure of a large number of receivables on the asset side to arrive in time, resulting in a liquidity gap, the first product overdue payment occurred. In order to avoid the expansion of risks, since July 19, all product offerings and redemptions on the debt rights of Zhongzhi Enterprise Group on the wealth side have been suspended. Zhongzhi was forced to enter the process of repaying investors' rights through workout.
In the course of more than 25 years of development, Zhongzhi Group has built a huge comprehensive enterprise group covering real industry, asset management, financial services, wealth management and other fields, holding more than ten listed companies, investing in coal and minerals, and holding trust, fund, property insurance, life insurance and other financial licenses. Its internal publicity materials say that the scale of assets under management has exceeded 3.70 trillion yuan.
In fact, the disorderly expansion of the mesophytes came to an end after Xie Zhikun's death.
In June 2021, the remaining 70% of the principal of Zhongrong Trust "Rongyu No. 100" was difficult to repay. The trust size of "Rongyu No. 100" was 1 billion yuan, the starting point of investment was 1 million yuan, and the reference annualized rate of return was 7.2% -8.2%. The investment period was 12 months and expired on January 15, 2021. The funds were used to increase capital to Huaxia Happiness Industry New Town (Xi'an Chang'an) Development Co., Ltd. However, in January, Huaxia Happiness was exposed to a shortage of funds and overdue debts.
However, due to the large scale of expansion in the past 10 years and the large downward cycle of real estate, the delayed initiative to reduce the scale of fundraising has been of no avail.
The main reason for the thunderstorm of Zhongrong Trust is the decline in the real estate cycle, the decline in the return on underlying assets corresponding to trust financing, and the inability to match the high returns that trust products need to pay, ultimately leading to the collapse of the capital chain and the failure of trust products to pay on time.
From the perspective of the underlying assets, those who borrow trust financing are basically the least qualified or the highest risk level of liabilities. And such high financing costs usually mean that the corresponding enterprises are difficult to operate. Most of these enterprises are related to the real estate chain.
Data show that the proportion of Zhongrong Trust's real estate business continues to grow, from 2017 to 2020,The proportion of trust assets invested in real estate is 6.61%, 10.99%, 17.65% and 18% respectively. Evergrande, Huaxia Happiness, Kaisa, Sunac, Sunshine City, Blu-ray Real Estate, Taihe and Shimao all cooperate with Zhongrong Trust.
In fact, if you carefully split the funds invested in trust products, most of them are related to real estate.
According to relevant data, the expected return rate of trust products is basically more than 8%. According to insiders of Zhongzhi, in addition to giving investors 8% -9% product income, financial advisors have a rebate of about 1%, plus various operating costs such as personnel and office rent, the comprehensive capital cost of Zhongzhi may reach 15% -16%. Such a high capital cost is difficult for the real industry to afford.
"The game is capital, only the capital game can afford it." Xie Zhikun, the former chairperson of Zhongzhi Group, once said that wealth companies are not required to make profits, as long as they can provide continuous financial support for the group's fundraising.
It can be seen that the Ponzi financing model of Zhongzhi's trust products has actually been revealed.
The summary record of the recent meeting of Zhongrong Trust is as follows:
First, the Zhongrong trust run crisis was influenced by the Zhonghua Group.
Second, it is impossible for Zhongrong Trust to continue to issue, borrow new ones to pay back the old ones, and delay the problem, so it cannot be sent out at all.
Third, now Zhongrong Trust is withdrawing capital everywhere, withdrawing liquidity, and surviving with a broken arm.
Fourth, due to the rise of self-media, information flows so rapidly that it is no longer possible to hide it.
Fifth, the investment portfolio has underlying assets, but it cannot be specifically disclosed to prevent changes and the time required to dispose of assets.
Sixth, still counting on real estate project assets in Shanghai and other places to recover investment.
Seventh, whether the portfolio can cover the redemption, I don't know, for example, the successful example of Huaxia Happiness, which has come back to life.
Eighth, the top leader is missing, too busy.
Ninth, the government requires the mainstream media not to report, repost and comment on the bad reports of Zhongzhi Group and Zhongrong Trust.
Tenth, Zhongrong Trust once invested in Hengda 67 billion, which was the only one who made money and ran away from Hengda.
Eleventh, there will be no salary cuts, and we must keep everyone's salary (the people below are talking: but the customers are gone).
Twelfth, we must stabilize and reassure customers.
Thirteenth, the speaker of the conference had all his wealth in Zhongrong Trust and had already lost two-thirds.
Fourteenth, the overall economic situation is declining, asset depreciation is very severe, and half of trust assets may be fixed assets such as real estate.
According to the ranking of the use of trust network, the total assets of Zhongrong trust ranked 9th in the trust company, the total assets of about 24.271 billion; comprehensive ranking of 11, has not yet entered the top 10. In recent years, under the background of strong financial supervision and risk prevention, the default of some products in Zhongrong does not mean that the overall risk of the trust industry is greater, and even will cause systemic risks in the financial industry.
Purchase of listed companies of Zhongrong Trust products: mainly in the biomedical, machinery and equipment, and automotive industries, most of which are small-cap companies.
Purchase of listed companies of Zhongrong Trust products (first-class industries): mainly in the biomedical, machinery and equipment, and automotive industries.According to Wind statistics, among the listed companies that have disclosed the purchase of Zhongrong Trust products, there are a total of 8 biomedical companies, 5 machinery and equipment companies, 5 automobile companies, 4 power equipment companies, 4 basic chemical companies, and 4 computer companies.
Purchase of listed companies of Zhongrong Trust products (secondary industry): mainly in the auto parts and chemical pharmaceutical industries.According to Wind statistics, among the listed companies that have disclosed the purchase of Zhongrong Trust products, there are 5 auto parts companies in total, 3 chemical and pharmaceutical companies in total, 2 IT service II companies in total, 2 Baijiu II companies in total, 2 publishing companies in total, 2 power grid equipment companies in total, 2 animal health II companies in total, 2 real estate development companies in total, 2 clothing and home textile companies in total, 2 chemical products companies in total, 2 environmental management companies in total, 2 household goods companies in total, 2 plastic companies in total, 2 general equipment companies in total, 2 medical apparatus companies in total, and 2 traditional Chinese medicine II companies in total.
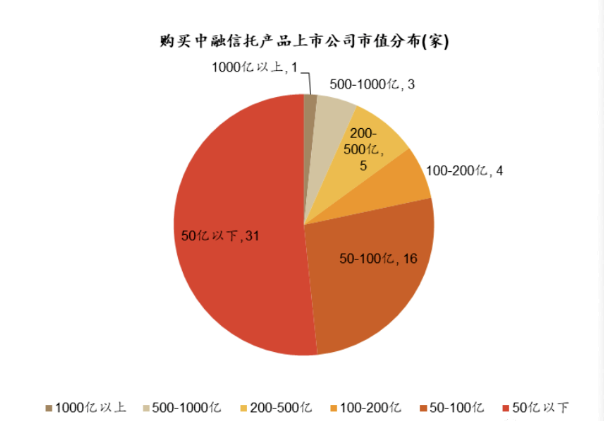
Market value distribution of listed companies that purchase Zhongrong trust products: mainly small-cap companies.According to Wind statistics, the listed companies that have disclosed the purchase of Zhongrong trust products, as of August 11, 2023, a total of 1 company with a market value of more than 100 billion, 3 companies with a market value of 500-100 billion, 5 companies with a market value of 200-50 billion, 4 companies with a market value of 100-20 billion, 16 companies with a market value of 50-10 billion, and 31 companies with 5 billion.
Zhongrong Trust has a small proportion in the trust industry, and in recent years, under the background of strong financial supervision and risk prevention, the situation of other companies is relatively stable. The default of Zhongrong Trust has a more emotional disturbance on class A shares, and the actual impact is small. And the listed companies held by trust companies are mainly concentrated in financial companies led by securities and banks, and the holdings in other industries are relatively scattered and small, which may have short-term impacts on non-bank finance, banks and a few involved companies.
FXTThe foreign exchange representation refers to history. The default of Zhongrong Trust has a small impact on the overall probability of class A shares, and may have a certain short-term disturbance to the non-bank financial and banking indices. We take the Sichuan Trust incident that defaulted in June 2020 as an example, which has certain reference significance for the impact of the class A share market. The CSI 300 index moved smoothly throughout June after the Sichuan Trust defaulted, and the news came out that there were no abnormal fluctuations in the stock index before and after the investor communication meetings on June 11 and June 24, 2020. Although the non-bank financial and banking index fell slowly in mid-June, it strengthened and rose in July. Even if the decline of the two stock indexes in June was affected by Sichuan Trust, the impact was short-term and small, and the stock index soon returned to normal.
Please indicate the source: https://www.daoctech.com/fxnews/589.html
Disclaimer: The content of this article does not represent the views of the Institute of Foreign Exchange. The content is for reference only and does not constitute investment advice. Investors operate accordingly at their own risk.