
St. Louis Fed warns: bond issuance frenzy could drain bank reserves, "force stop" QT
The Federal Reserve Bank of St. Louis said that with the US Treasury borrowing heavily in the short-term paper market, the Federal Reserve may be forced to pause its efforts to reduce the balance sheet to ensure the stability of the banking system.
Since the government suspended the debt ceiling in June, the US Treasury has sold about $1 trillion of Treasury bills. Cash to buy government bonds can come from at least two sources:Bank accounts or money market funds.
Recently, money market funds have been hesitant to buy Treasuries because they can usually earn more by storing their money at the Federal Reserve using an overnight reverse repurchase facility, or ON RRP.
St. Louis Fed economists Amalia Estenssoro and Kevin Kliesen wrote in a research note this week that if money to buy government bonds becomes overly reliant on the banking system, banks may find themselves with too little reserves to meet regulatory requirements.This could force the Federal Reserve to stop its quantitative tightening program (QT).。
"The risk is that bank reserves will remain a major part of the Fed's balance sheet contraction as QT persists," wrote Estansoro and Clayson. "In this case, banking regulatory restrictions could come into effect sooner than expected."
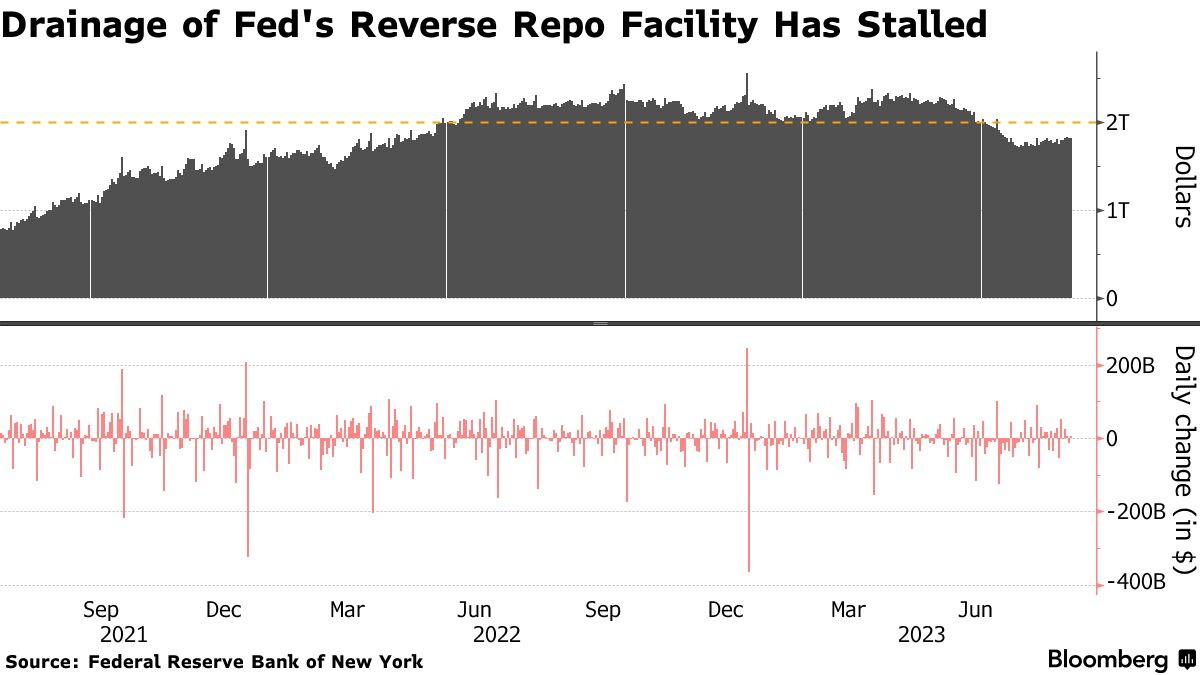
This risk is not just theoretical, it could be,The use of the Federal Reserve's overnight reverse repurchase facility appears to have stopped falling.
The scarcity of bank reserves has caused problems in the past, most notably in September 2019, when the Treasury increased borrowing and the Federal Reserve stopped buying as many Treasuries as it could for its balance sheet. Eventually, the overnight Treasury repo rate, on which Wall Street banks rely widely, soared, forcing the Fed to resume buying Treasuries to intervene and provide more liquidity to the banking system.
On the other hand, if purchases of government bonds are funded primarily by overnight reverse repurchase vehicles, the impact on the financial system may be manageable. This appears to be what happened to the financial system nearly three months ago. After the government suspended the debt ceiling, the use of overnight reverse repos fell to $1.717 trillion on July 18, but has since stabilized near $1.80 trillion.
Industrial foreign exchangeStrategists estimate the Treasury will issue another $600 billion between now and the end of the year, which economists say may not fully deplete the stock of overnight reverse repos in the second half of the year.
St. Louis Fed economists say that during the last round of QT about five years ago, bank reserves needed to be equal to about 7% of nominal GDP to prevent money market rates from spiking. Given current GDP, that would be equivalent to about $1.90 trillion.
But economists say it may make sense for banks to hold reserves above that level. In a recent survey of senior finance officials by the Federal Reserve, about 78 percent of bank representatives surveyed said their institutions would prefer to hold additional reserves above their minimum comfort level.
As Estansoro and Clayson write, "financial marekt continues to grow,Ideal liquidity could be close to 10% to 12% of nominal GDP ($2.70 trillion to $3.30 trillion).The current level of reserve balances across the banking system is already near the estimated upper limit. "
Please indicate the source: https://www.daoctech.com/fxnews/654.html
Disclaimer: The content of this article does not represent the views of the Institute of Foreign Exchange. The content is for reference only and does not constitute investment advice. Investors operate accordingly at their own risk.